
HDB Cooling, Condos Heating Up: Why the Upgrader's Window Is Open in Late 2026

If you've been waiting for the “right time” to move from your HDB flat to a private condo, the market has just handed you something unusual: two segments moving in opposite directions, and both of them working in your favour.
A tale of two markets
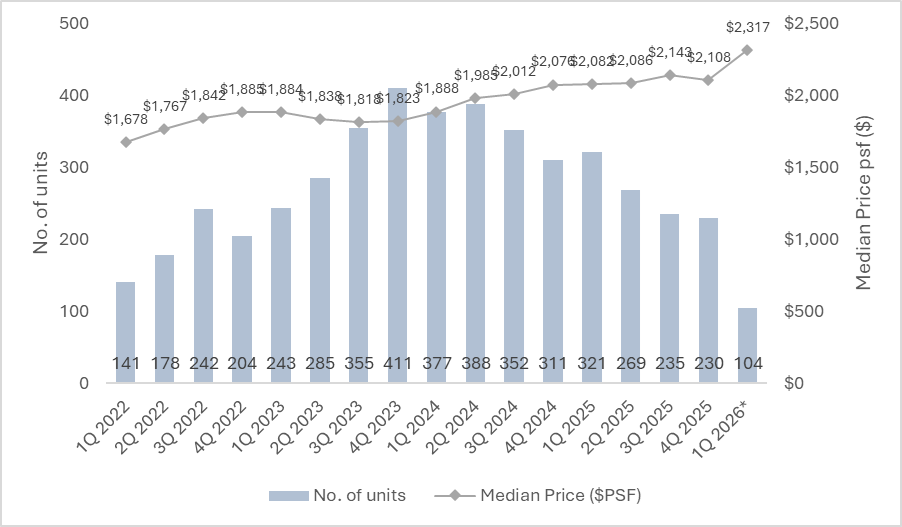
Right now, Singapore's property market is running on a split screen. On one side, private home prices are picking up pace — URA's flash estimate for the third quarter of 2026 shows private residential prices rose 1.4% quarter-on-quarter, nearly triple the pace seen at the start of the year. On the other side, the HDB resale market has quietly softened, with the resale price index easing over the past couple of quarters.
For most buyers, that sounds like a mixed bag. But if you're an upgrader — selling an HDB flat to buy a condo — it's a combination worth paying attention to.
Why this moment favours upgraders
Every upgrader's quiet fear is the same: “What if I sell low and buy high?” The beauty of the current market is that the usual pressure on the sell side has eased without the floor falling out. HDB resale prices remain near record levels — million-dollar flat transactions are still happening at record highs — even as the overall index cools. In other words, you can still command a strong price for your flat today.
Meanwhile, condo prices are climbing again. That matters, because waiting another year could mean buying into a noticeably steeper private market. The gap you're trying to cross tends to widen the longer you wait.
The financing tailwind most people overlook
Here's the piece many upgraders underestimate: borrowing has become meaningfully cheaper. Mortgage rates have eased below around 1.5%, tracking a lower SORA environment. In plain terms, that's more buying power and lower monthly repayments than you'd have faced just a year or two ago — which can make the jump from flat to condo far more comfortable than you might expect.
The rules to check before you move
Timing the market is only half the story; timing your own transaction is the other half. Before anything else, it's worth understanding three things:
Additional Buyer's Stamp Duty (ABSD) — the biggest factor in deciding whether to sell your flat first or buy your condo first. Getting the sequence right can save you a significant sum.
Loan-to-Value (LTV) limits — how much you can actually borrow against your new home.
Total Debt Servicing Ratio (TDSR) — the framework that determines your loan eligibility based on your income and existing commitments.
None of these are reasons to be discouraged. They're simply the moving parts, and sequencing them correctly is exactly where good advice pays for itself.
Is the window right for you?
A quick gut-check. It may be worth a conversation if your flat has met its Minimum Occupation Period (MOP), you're curious what it would fetch in today's market, you want to understand your realistic loan eligibility before you start viewing, or you're clear on whether you're buying for own-stay or investment.
The bottom line
Markets rarely hand upgraders a clean window — a firm resale price for the flat you're selling, a financing environment that stretches your budget further, and clear signals that private prices are on the move again. Late 2026 is shaping up to be one of those windows.
The smartest first step isn't a decision — it's information. If you'd like a no-obligation valuation of your flat and an honest view of your options, we're here to help you cross that gap with confidence.
This is your home advantage.
Market figures are accurate as of October 2026 and are intended as general information. Your ideal timing depends on your personal circumstances — do reach out for advice tailored to your situation.


Comments